When heavy rain moves through the Ozarks, water can rise fast. Most homeowners assume their insurance has them covered. The hard truth is that a standard homeowners policy does not pay for flood damage. That is why flood insurance is worth understanding before a storm ever hits. A little planning now can save you from a big bill later. Here is what every Springfield-area homeowner should know.
Why Flood Insurance Matters
Floods are the most common natural disaster in the country, and they are not picky about where they happen. Since your homeowners policy leaves flood damage out, flood insurance fills that gap. Most policies come through the National Flood Insurance Program (NFIP), a federal program that helps people rebuild after a flood.
It is easy to picture the worst case: losing your whole home. In reality, most claims are far smaller. According to FloodSmart.gov, the average NFIP claim payment is about $68,000, and policyholders never have to pay it back. That is not pocket change, but it shows that most claims are about repairs, not total loss.
What Flood Insurance Covers and What It Costs
NFIP coverage has limits, and it helps to know them before you buy. Here is how the coverage breaks down:
- Your home: Up to $250,000 for the structure itself.
- Your belongings: Up to $100,000 for the items inside.
- Combined cap: A total ceiling of $350,000 for a standard NFIP policy.
- Above the cap: Private or supplemental policies can cover higher-value homes.
If your home is worth more than $250,000, a supplemental policy can cover the difference. Your price will depend on your home’s value and how likely it is to flood.
You Do Not Have to Live in a Flood Plain
One of the biggest myths about flood insurance is that only homes in a flood plain need it. The numbers say otherwise. FloodSmart.gov reports that nearly one in three flood claims come from outside high-risk areas.
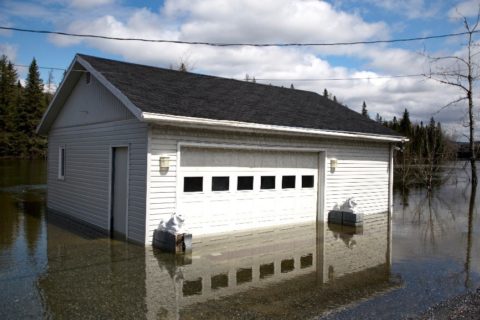
Think of a “Deer Crossing” sign. It marks where deer are often seen, but it does not mean that is the only place a deer will step into the road. Floods work the same way. If your property gets rain, it can flood. No home is completely safe.
Things People Get Wrong About Flood Insurance
Flood insurance comes with a few rules that surprise people. Keep these in mind so you are not caught off guard:
- The 30-day wait: Most policies do not start for 30 days, so you cannot buy coverage as a storm rolls in. Plan ahead.
- Not all water is equal: If a tornado tears off your roof and rain pours in, that is usually a homeowners claim. If you need a boat to reach your mailbox, that is flood damage.
- Water backup is separate: Damage from a failed sump pump often needs its own “water backup” add-on. Ask your agent about it.
- Flood maps change: You may not be in a flood zone today, but maps shift over time. Check with your agent or FloodSmart.gov.
One Thing to Watch in 2026
There is a timely reason to pay attention to flood insurance this year. The NFIP’s authority to write new policies must be renewed by Congress on a set schedule. The program was set to expire on September 30, 2026, and Congress extended it through December 11, 2026. Another extension is expected, but these deadlines have caused short pauses before. Here is what a lapse would and would not affect:
- Existing policies: They stay in force until they expire, including the usual grace period.
- Claims: They keep getting paid as long as funds are available.
- New and renewal policies: These would pause until Congress acts to reauthorize the program.
If you plan to buy or renew flood coverage near the December deadline, it is smart to act early and keep an eye on the news. Private flood insurance, which is not run through the NFIP, is not affected by this deadline.
Where Your Roof Fits In
Water damage is not only a flood problem. Your roof is your home’s first line of defense against rain, and most homeowners policies only cover storm-related roof damage, not normal wear and tear or damage from animals. That can leave you paying out of pocket.
This is where the Dale’s Roofing Stay DRI Maintenance Club helps. For less than $200 a year, members get annual inspections, gutter cleaning, repair discounts, and a record of every inspection visit. Those records can be a big help when you file an insurance claim. It is an easy way to keep your roof ready for whatever Ozarks weather brings.
Frequently Asked Questions About Flood Insurance
Here are quick answers to the questions homeowners ask us most about flood insurance.
Does homeowners insurance cover flood damage?
No. A standard homeowners policy does not cover flood damage. You need a separate flood insurance policy, usually through the NFIP or a private insurer.
How much is the average flood insurance claim?
According to FloodSmart.gov, the average NFIP claim payment is about $68,000, and policyholders do not have to repay it.
Do I need flood insurance if I am not in a flood zone?
You are not always required to, but it is still smart. Nearly one in three flood claims come from outside high-risk areas, so any home that gets rain can flood.
How long before flood insurance takes effect?
Most NFIP policies have a 30-day waiting period. That means you cannot wait for a storm to appear and buy coverage in time, so it pays to plan ahead.
Is the National Flood Insurance Program going away in 2026?
No. Congress has extended the NFIP through December 11, 2026, and it is expected to be renewed again. If it lapses for a short time, current policies stay in force and claims are still paid. However, new policies and some renewals may be put on hold until Congress acts.
Your roof is your home’s first defense against water. Keep it strong with the DRI Maintenance Club—call Dale’s Roofing at 417.882.2158 to learn more.